Most people can tell you what their car is worth.
They usually know the value of their home, the balance in their savings account and, with varying levels of enthusiasm, the amount still owing on their mortgage.
Ask them what their future income is worth, however, and the room becomes much quieter.
Yet income is the asset doing most of the work.
It pays for the home and the car. It services the debt. It funds the savings, investments and pension. It pays the insurance premiums, supports the family and keeps the ordinary machinery of life moving.
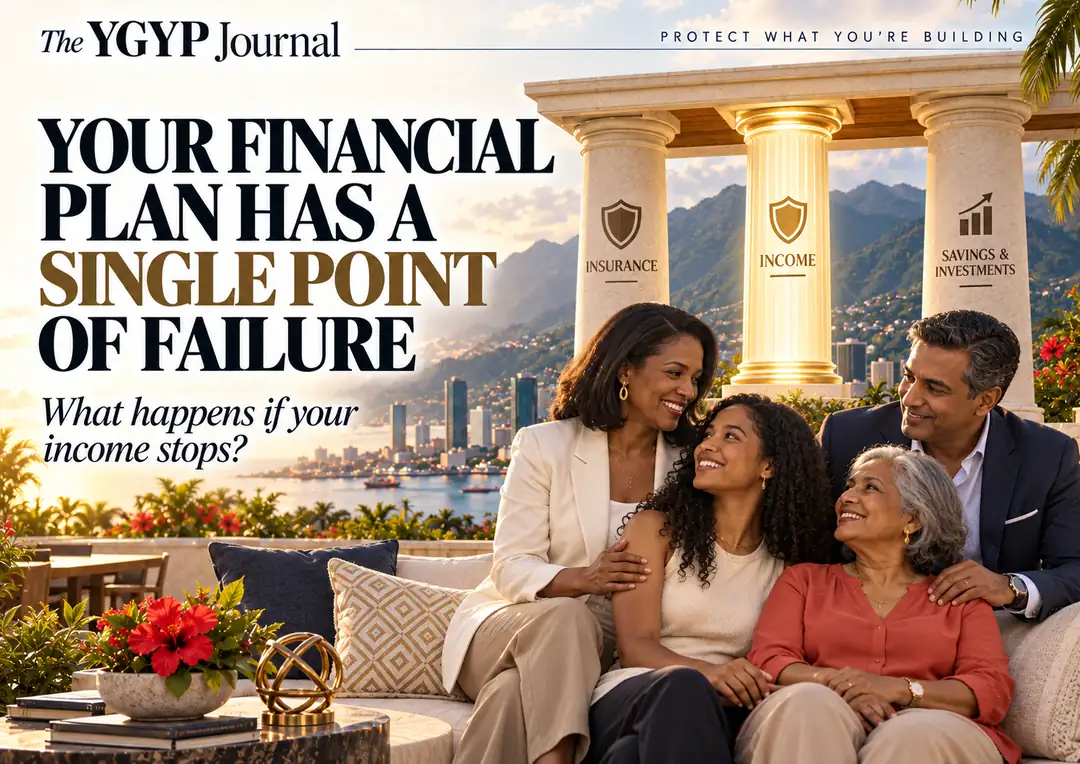
Your financial plan may contain several accounts, policies and goals—but many of them depend on one thing continuing to happen:
You must remain able to earn.
That makes income the engine of the plan. It can also make you its single point of failure.
We protect the things income buys
Insuring a vehicle feels obvious. So does protecting a home against fire, flood or another major loss.
These are visible assets. We can see them, value them and imagine the cost of replacing them.
Income is different. It arrives in instalments, so we tend to think of it one month at a time rather than as a long-term asset.
But consider someone earning TT$15,000 per month. Over ten years, that represents TT$1.8 million of gross income before allowing for any increases. Over twenty years, it is TT$3.6 million.
That does not mean every dollar would have been saved. It means those future paycheques were expected to finance a great deal of life.
When income stops unexpectedly, the loss is not confined to the next month. It can affect every goal that depended on the months after it.
The mortgage does not become sentimental. Retirement does not agree to wait politely. Children continue growing, bills continue arriving and the grocery remains impressively committed to being paid.
Protection is not pessimism
People sometimes avoid conversations about illness, disability or death because thinking about them feels negative.
But protection planning is not a prediction that something bad will happen. It is a decision about where the financial consequences would land if it did.
Without a plan, the risk remains. It is simply carried by your savings, your assets, your future goals or the people you love.
Insurance allows some of that risk to be transferred to an insurer, subject to the terms, limits and conditions of the contract. You accept a manageable, planned cost today so that a qualifying event does not create an unmanageable financial demand later.
That is not fear.
It is funding.
The Three Financial Legs
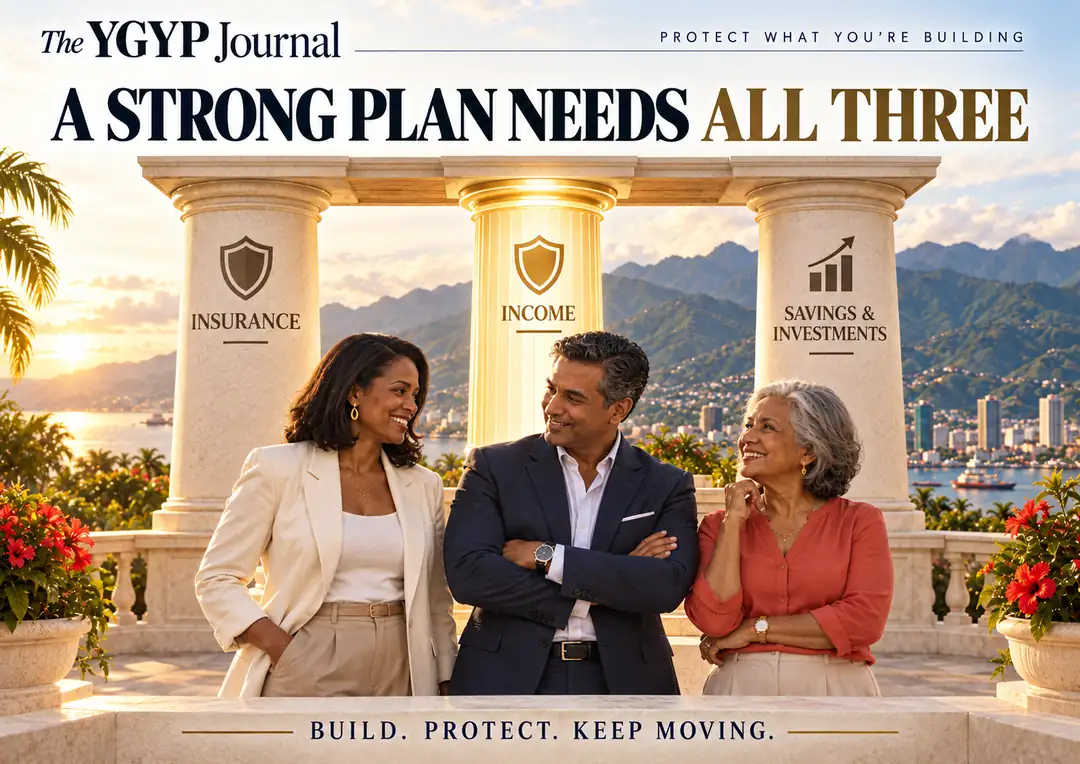
This is why the financial planning framework I use through Your Goals Your Plans begins with three connected financial legs.
Income sits at the centre. It provides the money that keeps the entire system operating.
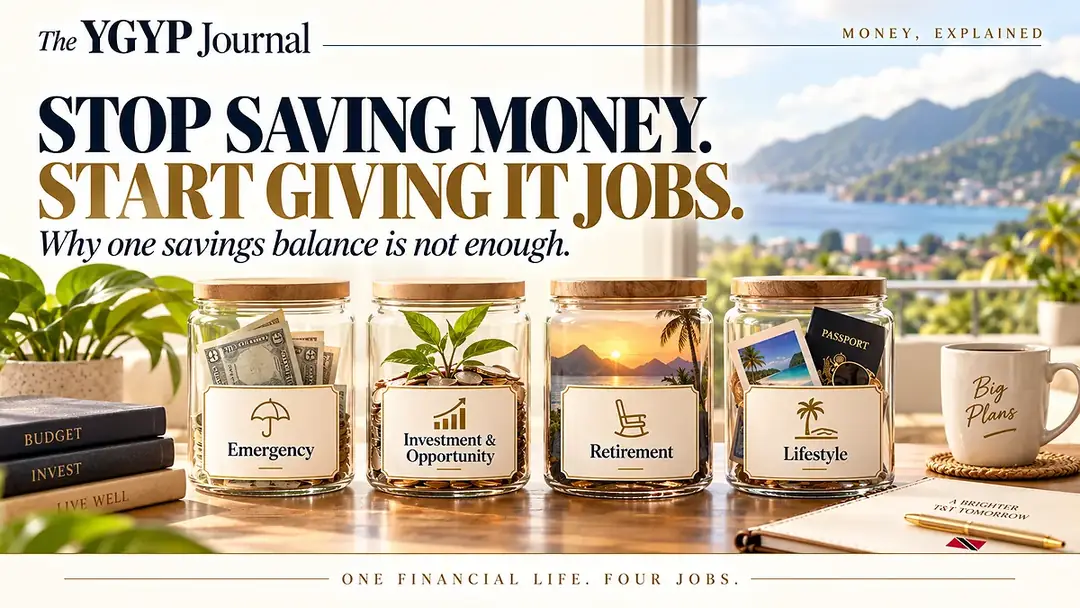
On one side are savings and investments: emergency reserves, opportunity funds, retirement savings, investments and money for lifestyle goals.
On the other side is insurance: protection for life, critical illness, accidents, disability income and health-related expenses.
Savings help you build. Insurance helps prevent a serious event from dismantling what you have built. Income feeds both.
Remove one leg and the plan becomes less stable.
This is also why buying a collection of financial products is not the same as having a financial strategy. The amounts, purposes and timing must connect to the life they are intended to protect.
What exactly are you protecting against?
“I have insurance” is a starting point, not a complete answer.
Different types of protection solve different financial problems.
Life insurance
Life insurance provides money to named beneficiaries when the insured person dies, provided the claim falls within the policy’s terms. Its job may include replacing income for dependants, settling debt, funding children’s needs, covering final expenses or helping a family retain important assets.
The useful question is not simply whether a policy exists. It is whether the benefit is connected to the amount and duration of the financial responsibility.
Critical illness protection
Critical illness coverage generally pays a lump-sum benefit following the diagnosis of a covered condition that meets the policy definition and any applicable requirements.
The diagnosis may not end a person’s career permanently, but it can create immediate costs and reduce income during treatment or recovery. That is why critical illness protection is ultimately as much about money as medicine: the financial problem can continue long after the immediate medical bill has been addressed. A lump sum can provide choices: time away from work, private care, household support, debt reduction or adjustments to the home and daily life.
Want to see how those costs can compound during a serious cardiac event? Try The Heart Bill.
Disability income protection
Disability income protection is intended to replace part of a person’s income when a qualifying illness or injury prevents them from working under the policy’s definition of disability.
This matters because surviving an illness and being financially able to recover from it are not always the same thing.
A person may be alive, receiving treatment and expected to improve—while the salary that normally pays the household has slowed or stopped.
Personal accident protection
Personal accident coverage responds to specified accident-related events. Depending on the contract, benefits may relate to accidental death, dismemberment, disability or income interruption.
Its scope is narrower than protection covering illness and other causes, which is why “I have accident insurance” should not automatically be translated as “my income is fully protected.”
Health insurance
Health insurance helps manage eligible medical costs. It protects cash flow and assets from some of the expense associated with care.
But paying a medical bill and replacing the income lost while someone cannot work are different financial needs. One form of coverage does not necessarily perform both jobs.
All benefits depend on the specific policy. Definitions, exclusions, waiting periods, benefit periods and claim requirements matter. The name on the brochure is not the contract.
“But I have savings”
Good. Savings should be part of the plan.
The previous Money, Explained article (Your Salary Is Doing Too Many Jobs), we made the case for financial reserves because cash is the first line of defence against ordinary disruption.
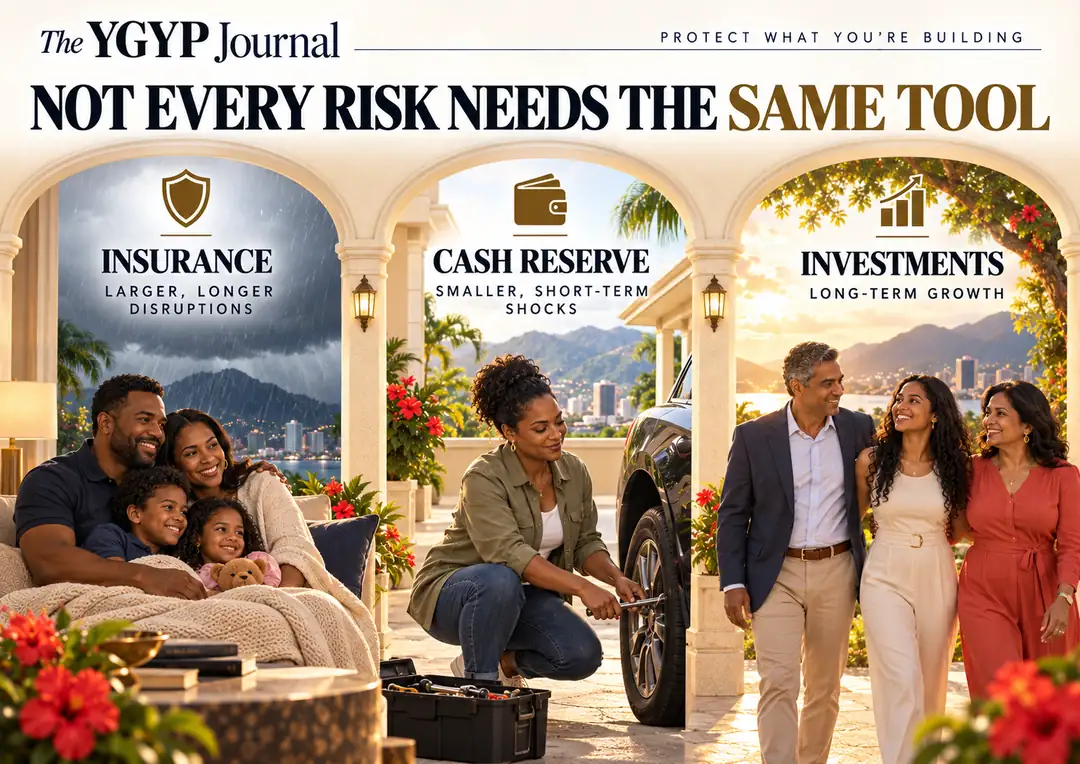
But cash and insurance are not rivals. They are designed for different scales of risk.
A reserve may comfortably handle a vehicle repair, an urgent household expense or a short interruption in income. It may not be the most efficient way to fund several years without earnings, a major critical illness or the permanent loss of a breadwinner’s income.
Self-insuring every serious risk would require most households to accumulate substantial money before the risk occurs. Insurance exists because the event may arrive before the savings do.
The stronger question is therefore not:
“Should I save or insure?”
It is:
“Which risks can my savings carry—and which ones would be too large?”
Employer benefits and NIS still need context
The National Insurance System in Trinidad and Tobago provides several benefits that can become relevant when someone’s ability to work is interrupted.
For example, eligible insured persons may qualify for Sickness Benefit where illness causes certified incapacity and loss of earnings. NIBTT states that Sickness Benefit can be paid for up to 52 weeks, subject to the applicable eligibility and contribution requirements.
NIS also provides an Invalidity Benefit for qualifying insured persons who are medically certified as likely to remain unable to work for at least 12 months, subject again to contribution and other eligibility requirements.
And where incapacity results from a qualifying work-related accident or prescribed occupational disease, the National Insurance System provides separate Employment Injury Benefits.
These benefits can be valuable.
But they should be understood rather than assumed.
NIBTT itself notes in its most recent published annual report that Sickness Benefit may not cover a person’s full loss of earnings.
Similarly, an employer may provide group insurance, paid sick leave or other benefits, but the important questions remain:
- What events are covered?
- How is eligibility determined?
- When do payments begin?
- How long do they continue?
- How much of your normal income would actually be replaced?
- And what happens to an employer-provided benefit if your employment ends?
A benefit existing somewhere in your employment package or contribution history is not the same as knowing what money would reach you, when it would arrive and how long it would last.
That’s where financial literacy becomes practical.
Run the interruption test
You do not need a complicated calculation to expose the first gaps.
Imagine that your income stops tonight.
Then answer these questions:
- What money is immediately available during the first 30 days?
- What continues funding the household after three months?
- Which debts and essential expenses continue regardless?
- Who depends on your income—and for how long?
- Which benefits could come from your employer or NIS?
- Which protection belongs to you personally?
- What happens to saving, investing and retirement contributions while your income is interrupted?
Do not answer with “I should be okay.”
Name the source. Name the amount. Name when it begins and when it ends.
If the answers are unclear, that is not a reason to panic. It is the beginning of the review.
Protection should change as life changes
The right protection at 30 may not be the right protection at 50.
Income changes. Debt rises and falls. Children become independent. Businesses grow. Employer benefits change. Retirement moves closer and the amount of future income still at risk gradually reduces.
Protection should therefore be reviewed—not purchased once and forgotten in a drawer beside appliance warranties and instruction manuals nobody intends to read.
The objective is not to own as much insurance as possible. It is to carry an appropriate amount of protection for the risks that could seriously disrupt your plan.
The bigger lesson
Financial planning is often presented as accumulation: save more, invest more and build more.
But building without protecting creates a plan that may look impressive while everything is going well and become fragile when life changes direction.
A resilient financial plan has to understand both sides of the equation: how to build financial capacity and how to protect that progress.
Because the home, the pension, the investments and the family’s future are not separate from your income.
They are being financed by it.
So ask yourself:
If you could not earn tomorrow, what would keep today’s financial plan alive?
Your answer will tell you whether you merely own protection—or whether you have actually protected what you are building.
Would Your Financial Plan Survive an Interruption in Income?
Knowing that you own insurance is different from knowing whether your household could withstand an interruption in income.
A Personal Protection Review can help identify what is already covered, what your savings could reasonably carry and where a significant protection gap may remain.
Sources & Further Reading
National Insurance Board of Trinidad and Tobago — Sickness Benefit
Official information on eligibility, loss of earnings and the period for which Sickness Benefit may be paid.
National Insurance Board of Trinidad and Tobago — Invalidity Benefit
Official information on long-term incapacity and contribution requirements for Invalidity Benefit.
National Insurance Board of Trinidad and Tobago — Employment Injury Benefit
Information on benefits arising from qualifying work-related injury or occupational disease.
NIBTT Annual Report 2023–2024
Provides broader context on NIS benefits and notes that Sickness Benefit may not replace the full loss of earnings.
This article provides general financial education and should not be treated as personalised financial advice or as a description of any particular insurance product. Coverage, definitions, exclusions, eligibility requirements and benefits vary by policy and provider. Individual financial circumstances differ.