Many of us inherited a financial script.
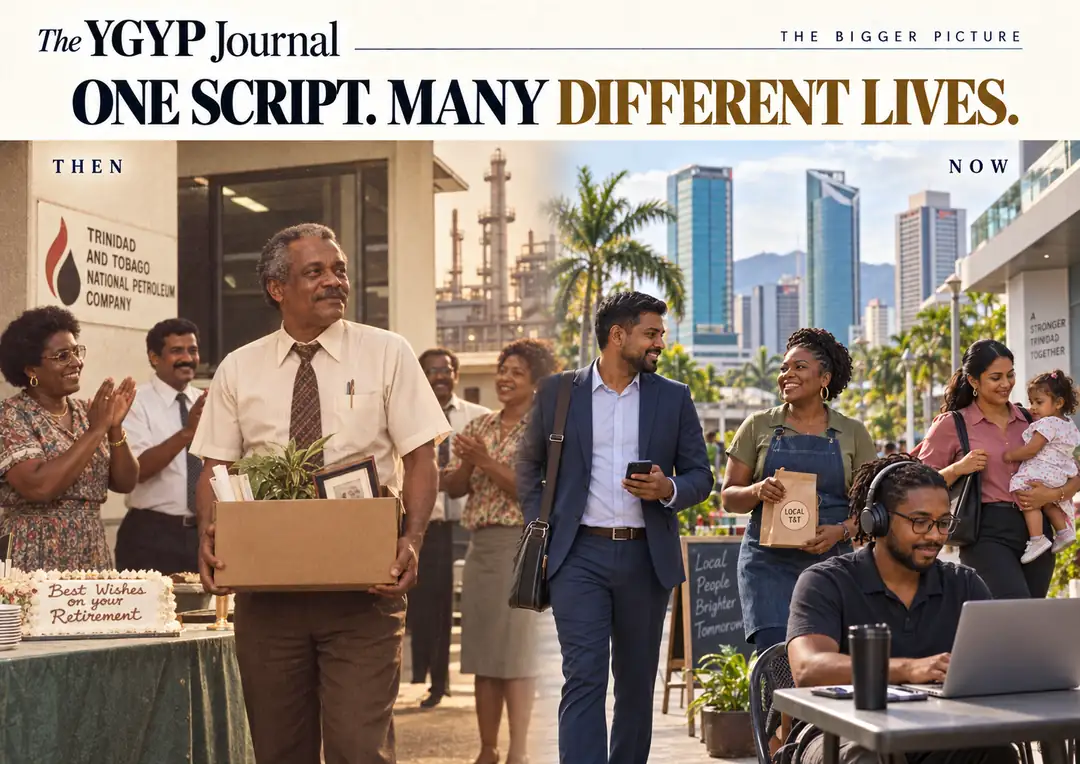
Get a good job. Work hard. Buy a home. Raise a family. Stay with the employer long enough to earn a pension. Retire at 60 and live comfortably thereafter.
It was never guaranteed, of course. Life has always had an unfortunate habit of editing the script without consulting the cast.
But the basic sequence felt dependable.
Today, it exists less as a plan and more as a piece of cultural memory.
People are changing jobs and careers. Some earn through contracts, commissions, small businesses or several sources at once. Employer pension arrangements vary. Families are supporting children for longer while also helping ageing parents. Retirement may last for decades. Public systems are changing under the pressure of longer lives and changing populations.
The old script still influences what we expect from money.
The world it was written for, however, has changed.
The old financial bargain
For much of the twentieth century, the idealised version of financial security rested on a bargain between the worker, the employer and the state.
The worker supplied decades of labour. The employer supplied a stable income and, in many cases, retirement benefits. The state provided a layer of social security. The family filled whatever gaps remained.
When all four parts worked, a person could arrive at retirement with a home, a pension and a reasonable expectation of support.
But that bargain depended on several assumptions:
- employment would remain relatively stable;
- wages would support the major costs of adult life;
- an employer or public pension would provide meaningful retirement income;
- retirement would not greatly outlast the working years used to prepare for it; and
- family members would be available to absorb financial shocks.
Those assumptions do not fit every modern life.
This does not mean the previous generation had everything easy. It means the risks were arranged differently.
We are carrying more of the responsibility ourselves
Whatever support may come from employers, family or the state, modern financial life requires individuals to make an enormous number of decisions for themselves.
You are expected to understand debt, build emergency savings, select suitable insurance, invest, prepare for retirement, manage healthcare costs and make decisions about financial products that may affect the next thirty years.
All while working, raising a family and remembering which password contains the capital letter and which one requires a symbol.
The number of decisions has grown. So has the consequence of getting them wrong—or simply making them too late.
This is one reason financial literacy matters so deeply.
Financial literacy is not the ability to repeat definitions about compound interest. It is the ability to understand the decisions in front of you, recognise the trade-offs and connect today’s choices to tomorrow’s life.
That is one reason financial literacy sits at the centre of Your Goals Your Plans and The YGYP Journal: to make the financial forces shaping everyday life easier to see, question and act upon.
A longer life changes the mathematics
Living longer is progress.
It also changes what financial security requires.
Trinidad and Tobago is also getting older. PAHO estimates that people aged 65 and over represented 12.4% of the population in 2024, up substantially from 2000. Its country profile also reports life expectancy as 73.6 years in 2024 and notes that population ageing is expected to accelerate in the decades ahead.
That does not tell any individual how long he or she will live. It does tell us why retirement planning increasingly has to account for the possibility of supporting income, healthcare and everyday life over a long period.
The planning question is no longer simply whether you will reach retirement with money.
It is whether your money—and the income it can produce—can remain useful throughout an uncertain period whose length you do not know in advance.
That is a different problem.
It requires us to think beyond a retirement date and consider future income, inflation, housing, health, debt, family obligations and the possibility of living much longer than expected.
The goal is not to fear a long life.
It is to fund one.
Work does not always follow one straight line
The traditional financial plan often assumed one career and a steady upward path.
Modern working lives can include redundancies, career changes, periods of self-employment, contract work, caregiving breaks, business ownership and income that rises and falls.
Even a person with a stable profession may move between employers and receive different combinations of salary, pension and health benefits along the way.
That makes portability important.
Some parts of your financial plan should belong to you—not only to the job you currently hold.
Employer benefits may be valuable, but you should know what happens when you leave. A retirement plan may be growing, but you should understand when its income begins. Insurance may exist through work, but you should know its amount, purpose and whether it continues after employment ends.
“My job provides something” is not yet a financial analysis.
Family money is rarely individual money
Personal-finance advice often imagines one person making decisions inside a beautifully organised spreadsheet.
Real financial life in Trinidad and Tobago is usually more communal.
Income may support children, parents, siblings, extended relatives or a family business. A household may be helping an adult child establish a career while also preparing an older parent for retirement. One person’s emergency can quickly become several people’s expense problem.
This interdependence is not inherently bad. It can be one of the great strengths of family life.
But support without structure can quietly prevent everyone from becoming secure.
Family responsibility should therefore be part of the plan, not treated as an occasional exception to it.
Who depends on you? What support is temporary? What may continue for years? Which needs require savings, insurance, shared responsibility or a difficult conversation?
Love may be unlimited.
Income generally is not.
A good income is no longer the whole answer
In Your Salary Is Doing Too Many Jobs, we looked at what happens when one stream of income is expected to fund today’s living costs, absorb disruption and finance tomorrow at the same time.
That pressure reveals an important shift.
Financial security is not simply the amount you earn. It is your capacity to continue when circumstances change.
A person may have a strong income and still be financially fragile if every dollar is committed, debt is high, protection is weak and no reserves exist.
Another person may earn less but have manageable commitments, accessible savings, suitable protection and several years of steady retirement preparation.
Income matters enormously.
But resilience is what keeps income from being the only thing standing between stability and crisis.
Certainty is no longer a sensible planning strategy
People sometimes postpone planning because too much is unknown.
They are waiting to know exactly when they will retire, how long they will work, what inflation will do, what government policy will become or which family responsibilities will appear.
Those answers may never arrive together.
Trinidad and Tobago’s National Insurance System provides a useful example of why long-term assumptions cannot simply be frozen in place. NIBTT’s actuarial work has documented increasing demographic pressure as the number of pensioners grows relative to contributors. Its Eleventh Actuarial Review projected that the ratio could move from about 2.4 contributors per pensioner in 2021 to fewer than one contributor per pensioner by 2070 if the underlying assumptions unfolded as projected.
These are long-range actuarial projections rather than predictions of an individual’s retirement outcome. But they illustrate the broader point: financial systems have to adjust when demographics and economics change.
A strong plan is not one that correctly predicts every future event. It is one that can adjust when the prediction is wrong.
That means building flexibility:
- cash reserves that create time;
- protection that transfers risks too large for savings to carry;
- savings and investments with different time horizons;
- retirement income from more than one possible source;
- debt that remains manageable when income changes; and
- regular reviews that keep the plan connected to real life.
The plan should not be a monument to decisions made ten years ago.
It should be a living system.
What remains within your control
The bigger picture can feel overwhelming because many of its forces are outside individual control.
You cannot personally set inflation, rewrite pension legislation or guarantee that an employer will remain unchanged for the next twenty years.
But you can improve the strength of your response.
You can understand where your income goes. You can build reserves gradually. You can protect the income and people supporting the plan. You can create assets intended to produce future income. You can review employer and state benefits rather than assuming what they will provide. You can make decisions earlier, while more options remain available.
This is the thinking behind the Three Financial Legs framework I use at Your Goals Your Plans: a simple way to see the major parts of financial security as one connected system.
Insurance stands on the left. Income is at the centre. Savings and investments stand on the right.
Income keeps the plan moving.
Savings and investments help you grow financially for the future you want.
Insurance protects against risks that may be too large—or last too long—for savings to carry alone.
The three legs do not remove uncertainty.
They give you a stronger position from which to meet it.
The bigger lesson
The old rules imagined security through permanence: one job, one path, one pension and one expected retirement age.
The newer reality requires security through adaptability.
That does not mean abandoning the traditional goals of home ownership, retirement or providing for family. It means recognising that reaching those goals may require more personal planning, more than one source of future income and a financial structure capable of surviving change.
The future does not need to be perfectly predictable for you to prepare for it.
It needs to be taken seriously.
So ask yourself:
Is your financial plan designed for the life you are actually living—or for the world the old rules assumed?
The answer may be the beginning of a much stronger plan.
Does Your Financial Plan Still Fit Your Life?
A financial plan should change as your income, responsibilities, goals and circumstances change.
Take the 1-Minute Money Alignment Check to see which part of your financial plan may need attention next.
Sources & Further Reading
Pan American Health Organization — Trinidad and Tobago Country Profile
Population ageing, demographic change and life expectancy data for Trinidad and Tobago.
National Insurance Board of Trinidad and Tobago — Eleventh Actuarial Review of the National Insurance System
Long-term actuarial analysis of changes in the relationship between contributors and pensioners and other demographic pressures facing the NIS.
Government of Trinidad and Tobago — National Financial Inclusion Survey Report 2023
Local research on financial inclusion, savings behaviour and access to financial services. The report describes a complex and evolving financial landscape and found that approximately 75% of households had an account with a financial institution in 2023.
This article provides general financial education and should not be treated as personalised financial, investment, insurance, pension or tax advice. Individual circumstances differ, and product terms, benefits and legislation may change.